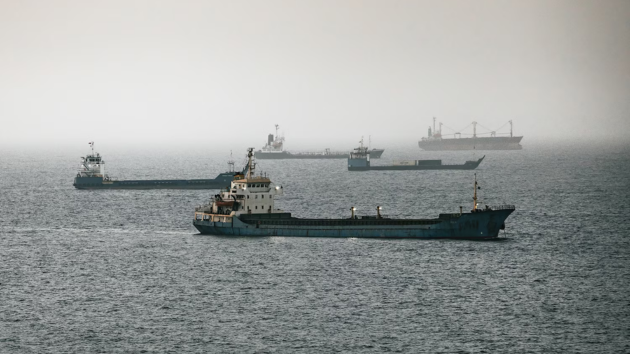
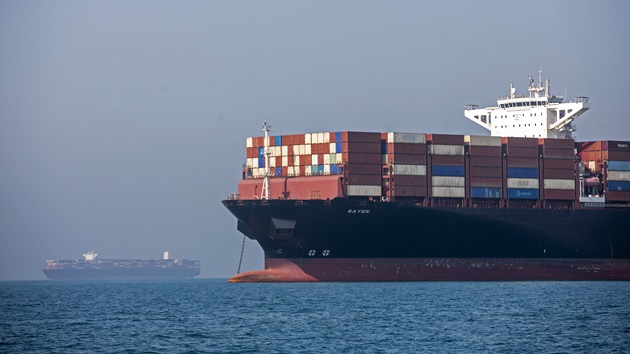
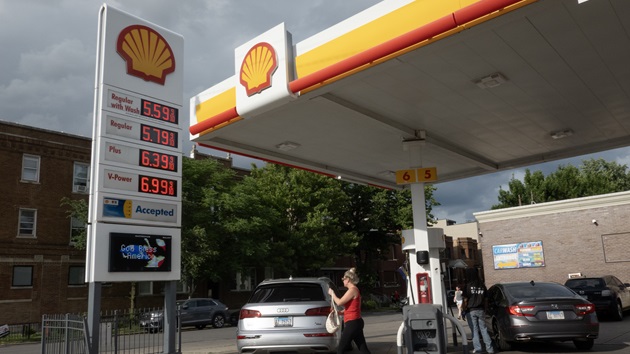
Crude oil tankers, bulk carriers and vessels sit anchored around Qaboos Port June 22, 2026, in Muscat, Oman. The Strait of Hormuz, a vital shipping route for the region’s oil and gas. (Elke Scholiers/Getty Images)
(NEW YORK) — Mortgage rates have dropped to their lowest level since May as negotiations between the United States and Iran ease financial markets.
The average interest rate on a 30-year fixed mortgage stands at 6.43%, down from last week’s rate of 6.49%, Freddie Mac data on Thursday showed.
Still, mortgage rates register above their level before the war with Iran. Prior to the Middle East conflict in late February, a 30-year fixed mortgage clocked in at an average just below 6%.
“Rates did drop, which does provide some relief. But they’re still high,” Julia Fonseca, a professor at the Gies College of Business at the University of Illinois at Urbana-Champaign, told ABC News.
A decline in mortgage rates over recent weeks has come in response to a drop in oil prices and Treasury yields, some analysts told ABC News. The shift has partially reversed a trend that took hold after the Iran war broke out.
At that time, mortgage rates surged in response to a jump in U.S. Treasury yields, or the amount paid annually to a holder of government debt. The rise in bond yields is owed to fear of a renewed bout of inflation as oil prices climbed.
Since bonds pay a given investor a fixed amount each year, the specter of inflation risks higher consumer prices that would eat away at those annual payouts. In turn, bonds often become less attractive in response to economic turmoil. When demand falls, bond yields rise.
High bond yields make borrowing more expensive for average Americans, since 10-year Treasury rates influence the rates offered for a variety of loans, including mortgages.
Bond yields eased in recent weeks as negotiations unfolded between the U.S. and Iran, pushing down oil prices and softening inflation expectations, Ken Johnson, a real estate economist at the University of Mississippi, told ABC News. In turn, Johnson said, mortgage rates have fallen.
“The big driver has been the cooling of tensions in the Gulf,” Johnson told ABC News.
Despite the recent drop, mortgage rates remain higher than their pre-war level. Even more, mortgage rates stand well above their level as recently as 2022, when the average rate on a 30-year fixed mortgage came in below 5%.
Elevated mortgage rates have contributed to a phenomenon known as the “lock-in” effect.
Mortgage rates remain well above the rates enjoyed by most current homeowners, who may be reluctant to put their homes on the market and risk a much higher rate on their next mortgage.
“Rates are still pretty high relative to what they were a few years ago, but every drop in mortgage rates helps. This is not going to go all the way toward unlocking people. We might see this gradual unlocking as time goes by and as rates tick down,” Fonseca said.
HR recruitment manager holding resume in hands while having an interview in a modern office. (Xavier Lorenzo/Getty Images)
(NEW YORK) — Hiring slowed markedly in June, falling short of economists’ expectations and displaying a wobbly labor market amid elevated inflation set off by the Iran war.
The U.S. added 57,000 jobs in June, according to the federal government’s monthly jobs report, which marked a decline from 172,000 jobs added in May.
The sluggish pace recorded in June departs from strong performance for the labor market so far in 2026. Employers added a robust average of about 114,000 jobs each month from January to May, Bureau of Labor Statistics (BLS) data showed.
The unemployment rate fell slightly from 4.3% in May to 4.2% in June, the BLS said. Unemployment remains low by historical standards.
The professional and business services sector led job gains, adding 36,000 positions in June. Significant job gains also came in healthcare, though the pace of job growth slowed in that sector.
Hiring had proven unexpectedly resilient, despite a rise in costs borne by businesses and shoppers.
The Middle East conflict, which began on Feb. 28, prompted the Iranian closure of the Strait of Hormuz, a maritime trading route that facilitates the transport of about one-fifth of the global oil supply. The standoff triggered one of the largest oil shocks ever recorded.
The pace of annual inflation stands at 4.2%, clocking in at more than twice the Federal Reserve’s target rate of 2%.
The combination of elevated inflation and a resilient labor market has raised the chances of an interest rate hike, futures markets show, posing a risk for corporations eager to keep borrowing costs relatively low.
Federal Reserve Chair Kevin Warsh briefly sent stocks tumbling this month during his first press conference atop the central bank. Warsh voiced a commitment to bringing inflation down to the Fed’s desired level.
“Persistently high prices are a burden for the American people,” Warsh told reporters in Washington, D.C. “This committee will deliver price stability.”
Futures markets peg the odds of an interest rate hike in September at about 64%, according to the CME Group’s FedWatch Tool, a measure of investor sentiment.
To be sure, the path forward for interest rates remains highly uncertain. Oil and gasoline prices have eased in recent weeks in response to negotiations between the U.S. and Iran, offering hope of a cooldown of inflation in the absence of rate increases.
On Wednesday, Warsh weighed in on the bullish side of an ongoing debate among policymakers, investors and the general public about the potential impact of AI on the labor market and wider economy.
The technology could create jobs and boost productivity, strengthening the economy of the U.S. and other nations, according to Warsh.
“This is a big paradigm shift both for the conduct of our policy and for our economies,” Warsh said. “I think the jobs will be greater. Prosperity will be stronger.”
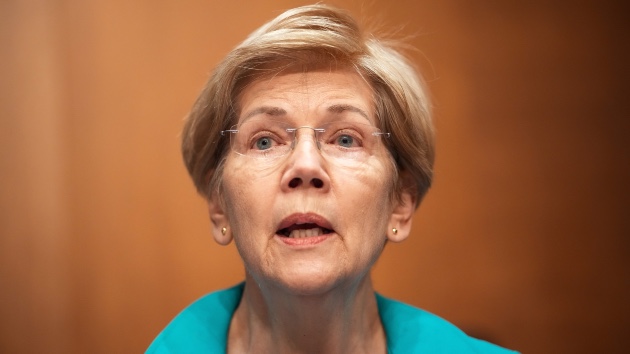
Ranking member Sen. Elizabeth Warren (D-MA) delivers an opening statement during the Senate Committee on Banking, Housing, and Urban Affairs confirmation hearing for Kevin Warsh, U.S. President Donald Trump’s nominee for Chair of the Federal Reserve, in the Dirksen Senate Office Building on April 21, 2026 in Washington, DC. (Photo by Andrew Harnik/Getty Images)
(NEW YORK) — The Social Security fund will run out of money in as little as six years, a shorter time frame than previously estimated, according to a report released earlier this month by the programs’ trustees.
News of the funding cliff prompted a pair of lawmakers to reach across the aisle and propose a rescue plan in an opinion piece last week for the New York Times.
Sen. Bernie Moreno, R-Ohio, and Sen. Elizabeth Warren, D-Mass., called for lifting a cap on the amount of annual income subject to the payroll tax that funds Social Security. Currently, the cap stands at $184,500.
In other words, the plan would require individuals making more than $184,500 per year to pay taxes on the entirety of their income, potentially generating trillions in additional funds for the program over the next 10 years.
The proposal could, in theory, help administrators avoid painful solutions for recipients, such as a reduction of Social Security payments.
Legislation reflecting the proposal has not been introduced. In the New York Times, Moreno and Warren said they are “working on legislation.” Spokespeople for Moreno and Warren declined to comment on the status of the measure.
Here’s what to know about a new bipartisan proposal for safeguarding Social Security:
Is Social Security in financial trouble?
Yes, the program faces an ever-tightening budget squeeze over the next handful of years, according to a report this month from the Social Security fund’s trustees.
The Social Security trust fund will run dry in 2032, unless Congress combines the program’s old-age and disability funds, in which case insolvency would arrive in 2034, the report found. A finding last year from the program’s trustees predicted Social Security would become insolvent in 2033 or 2034.
The program generates revenue through a payroll tax paid by employees and employers, setting the income apart from the overall federal budget. Since the early 2010s, however, Social Security has paid more in benefits than it takes in through taxes, shrinking the program’s available funds, according to a study issued by the Urban Institute earlier this year.
The budget shortfall has been exacerbated by a decline in births and a reduction of immigration, resulting in fewer taxpayers at the same time that many Baby Boomers have begun receiving benefits. The One Big Beautiful Bill also removed a tax on Social Security benefits, depleting another source of the program’s revenue.
What is the Social Security reform proposal from Warren and Moreno?
The bipartisan reform proposal would tweak the payroll tax that funds Social Security.
The program is funded by a 12.4% payroll tax, which is evenly split between employers and workers. The tax, however, applies only to a maximum of $184,500 in annual income, meaning any income beyond that amount remains tax free.
The proposal put forward by Warren and Moreno would lift the cap on taxable income, allowing the tax to apply to the entirety of a person’s income even if they make more than $184,500 per year.
“Since the vast majority of Americans make less than that, most people are paying Social Security taxes on 100 percent of their earnings while the highest earners are paying on only part of theirs,” Warren and Moreno said in a co-authored opinion piece in the New York Times.
The elimination of the cap on taxable income would generate about $3.4 trillion in added revenue over the next decade, according to an analysis from the non-partisan Peterson Institute. The policy change would close more than half of the program’s funding gap, the group said.
“With rising prices and artificial intelligence causing economic uncertainty for the future, Social Security must remain a stable foundation to help retirees afford life’s basic necessities,” Warren and Moreno said.
The proposal drew opposition from at least one conservative lawmaker. Sen. Jon Husted, R-Ohio, faulted the plan for what he described as a “giant tax increase.”
“We need to secure social security, we need to protect it, we need to make it stronger,” Husted told “The Guy Benson Show” last week. “But I’m not on board with the approach that they’ve outlined.”
What are some alternative reforms for funding Social Security?
As the program’s budget woes have deepened in recent years, elected officials and researchers have proposed a range of solutions. As with any financial shortfall, the fixes either increase revenue or slash expenses.
An alternate means of increasing tax revenue for the program involves ratcheting up the payroll tax by one percentage point from 12.4% to 13.4%, the Peterson Institute said. That move would generate $601 billion in additional revenue over 10 years, closing about a quarter of the program’s funding gap, the group added.
If Congress fails to address the projected budget shortfalls, automatic cuts will dial back Social Security benefits by about 25% in 2032, the Social Security fund’s trustees said earlier this month.
Earlier this month, a bipartisan bill introduced in the House proposed establishing an independent commission composed of 13 members appointed by leaders in Congress and the president. The commission would seek out fixes for the long-term sustainability of the program. The bill, which counts three cosponsors, has been appointed to two House committees for consideration.
As the years pass, the task of reforming Social Security becomes a greater and greater challenge, the Urban Institute said.
“Waiting only makes the changes larger and more difficult,” the group added.
Businessman typing on laptop computer keyboard at desk in office. (tadamichi/Getty Images)
(NEW YORK) — Federal Reserve Chair Kevin Warsh on Wednesday voiced optimism about artificial intelligence, describing the technology as a “paradigm shift” that would likely make the United States a “big winner in the medium-term.”
“We are in the first or second inning of this revolution,” Warsh said in Sintra, Portugal, at a conference organized by the European Central Bank.
Warsh, who took the helm of the Fed last month, weighed in on the bullish side of an ongoing debate among policymakers, investors and the general public about the potential impact of AI on the labor market and wider economy.
The technology could create jobs and boost productivity, strengthening the economy of the U.S. and other nations, according to Warsh.
“This is a big paradigm shift both for the conduct of our policy and for our economies,” Warsh said. “I think the jobs will be greater. Prosperity will be stronger.”
Business investment in AI has helped drive recent U.S. economic growth, some studies show.
A surge of AI spending accounted for roughly two-thirds of gross domestic product growth over the first half of 2025, JPMorgan Asset Management found, outpacing the contribution made by hundreds of millions of U.S. consumers. Many of the nation’s largest companies have poured funds into the chips and data centers necessary to operate AI.
AI chipmakers, meanwhile, have helped deliver stock market gains this year, allowing the major indexes to overcome a lackluster stretch for many of the tech giants that previously lifted markets.
Shares of fast-rising AI chipmakers have boosted major indexes. Micron has soared 265% in value this year. Sandisk has climbed a staggering 750% over that period.
For now, however, AI has failed to achieve gains on a scale near its immense costs, some analysts previously told ABC News. A product like AI would typically generate revenue in the form of sales either direct to consumers or to third-party businesses using the technology to enhance their offerings. AI has faced challenges on both fronts, some analysts said.
Speaking on Wednesday, Warsh signaled that he expects a shift in sentiment among businesses regarding the impact of AI.
“While we might see business surveys that say ‘no big deal,’ my speculation is six months from now the surveys will be saying quite the opposite,” Warsh said.
New York City Mayor Zohran Mamdani and NYC Congressional candidate Claire Valdez embrace during a primary-night watch party, June 23, 2026, in Brooklyn. (Michael M. Santiago/Getty Images)
(NEW YORK) — A trio of progressive Democrats sharply criticized billionaires on their way to victory in House primaries in New York City.
The clean sweep for candidates endorsed by far-left New York City Mayor Zohran Mamdani on Tuesday drew attention to economic populism as affordability remains a top issue for voters ahead of the midterm elections.
In Manhattan and Brooklyn’s 10th District, incumbent Rep. Dan Goldman lost in a landslide to former comptroller Brad Lander, who vowed to “put working people first – not billionaires.”
Darializa Avila Chevalier, a community organizer, defeated incumbent Rep. Adriano Espaillat in New York’s 13th District, which covers upper Manhattan and the Bronx. Claire Valdez, a one-term state assemblymember, beat Brooklyn Borough President Antonio Reynoso in the primary race for New York’s 7th District.
Valdez and Chevalier, both of whom are democratic socialists, called for a four-day work week and a pause in the construction of AI data centers, among other measures.
To be sure, center-leaning candidates won Democratic primaries on Tuesday in upstate New York and Utah. New Jersey Gov. Mikie Sherrill and Virginia Gov. Abigail Spanberger, who are both Democrats, won general elections last year with moderate campaigns touting their own plans to ease price woes.
Here’s what to know about economic proposals put forward by Lander, Chevalier and Valdez:
Tax on billionaires
All three of the victorious progressive House candidates support a tax on wealthy individuals.
Lander “strongly supports” the Ultra-Millionaire Tax Act, a bill proposed by Democratic Sen. Elizabeth Warren that would tax the net wealth of households with over $50 million, according to Lander’s website.
Lander also backs an ultra-wealth tax on individuals worth over $1 billion, as well as the Equal Tax Act, which matches tax rates for capital gains and ordinary income over $1 million.
Chevalier supports the Ultra-Millionaire Tax Act and the Equal Tax Act. Similarly, Valdez has voiced support for taxing billionaires as means of funding social programs.
The top opponents in each of the three primary races held similar positions. Both Espaillat and Goldman had signed on to the Ultra-Millionaire Tax Act and the Equal Tax Act. Reynoso said he would “fight to tax the rich – a lot.”
Proponents say wealth taxes could raise tax revenue from affluent Americans in a position to spare funds. Critics, on the other hand, warn wealthy individuals may move assets abroad or prove less likely to start businesses or other ventures.
For his part, Mamdani sought a two-percentage-point tax increase for residents making more than $1 million, which would have raised the tax rate for high earners in New York City from roughly 3.9% to 5.9%.
Instead, New York enacted a tax on second homes in New York City valued at $1 million or more.
Pause on construction of AI data centers
All three progressive House candidates back a moratorium on the construction of AI data centers.
Many of the nation’s largest companies have poured funds into the chips and data centers necessary to operate AI.
The data center projects have drawn ire from critics who say they drive up residential water and electricity bills in some areas, while offering limited job gains. Proponents of the sector point to its role in fueling economic growth and ensuring the competitiveness of U.S. tech firms.
Sen. Bernie Sanders, I-Vt., and Rep. Alexandria Ocasio-Cortez, D-N.Y, have proposed the AI Data Center Moratorium Act, which would pause the development of data centers until the federal government imposes industry regulations.
Goldman, Lander’s opponent, signed onto the AI Data Center Moratorium Act. By contrast, Espaillat – Chevalier’s opponent – has not supported the bill. Reynoso’s position on a data center moratorium could not be immediately found.
On her campaign website, Valdez said she would “fight to hold major technology corporations accountable, protect our workforce from the harms of AI, and ensure that new technologies benefit communities, not just corporate executives.”
Four-day work week
Chevalier and Valdez support shifting from a standard workweek of 40 hours spread across five days to one lasting 32 hours across four days.
Such an approach, Valdez says, would reclaim the “economic gains of automation for workers.”
Spain, Iceland and South Africa are among the nations that have implemented a trial of the four-day workweek for select companies and workers.
In California and the U.S. House, lawmakers have introduced bills that would set the standard workweek at 32 hours.
The Thirty-Two Hour Workweek Act, introduced in the U.S. House in March 2023, garnered support from eight members. Neither Goldman nor Espaillat was among the backers.
Reynoso’s position on a four-day workweek could not be immediately found, though last month he spoke in support of unionized Kickstart employees seeking a four-day workweek as part of their labor contract.
Some experts previously told ABC News that a combination of escalating market pressure and legislative activity could ultimately bring a nationwide four-day workweek standard; others said such an outcome would prove nearly impossible, at least anytime soon.
Labor law reform
The share of unionized workers has fallen nationwide in recent decades. All three of the New York City progressives say they want to reverse that.
Lander, Valdez and Chevalier each support the PRO Act, a labor law reform measure with strong backing among U.S. labor unions.
The legislation would ease the path toward forming unions and winning labor contracts. The latest version of the bill, known as the Richard L. Trumka Protecting the Right to Organize Act, boasts the support of 215 House members, including at least one Republican.
Both Goldman and Espaillat signed onto the PRO Act. Reynoso, meanwhile, vowed to “champion the PRO Act.”
On her campaign website, Chevalier calls for passage of the PRO Act, so that “everyone who wants a union can form one.”
A cargo ship remains anchored on May 16, 2026 in the Strait of Hormuz near Larak Island, Iran. (Majid Saeedi/Getty Images)
(NEW YORK) — Global oil prices on Wednesday fell to their lowest level since before the outbreak of the Iran war.
Brent crude futures, the benchmark index for worldwide trading, dropped to $73.50 a barrel. That figure, which amounted to a nearly 5% decline on Wednesday, marked the lowest price since Feb. 27, the day before the Middle East conflict began.
Stock prices, meanwhile, ticked higher Wednesday after a down day Tuesday. The Dow Jones Industrial Average jumped 105 points, or 0.2%, while the S&P 500 increased 0.2%. The tech-heavy Nasdaq rose 0.2%.Gas prices fell below $4 per gallon last week, crossing the milestone as oil costs eased in response to negotiations between the U.S. and Iran to end the war.
The national average price of a gallon of gas stands at $3.92, marking a decline of 58 cents, or 13%, over the past month, AAA data showed. Gas prices, however, remain 94 cents higher than where they stood before the Iran war.
The Middle East conflict prompted the Iranian closure of the Strait of Hormuz, a maritime trading route that facilitates the transport of about one-fifth of the global oil supply. The standoff triggered one of the largest oil shocks ever recorded, sending gasoline prices higher.
Delegations from the United States and Iran arrived over the weekend at the Bürgenstock resort in Switzerland, where they began negotiations aimed at a war-ending deal based on a memorandum of understanding signed last week by both countries.
The memorandum in part called on Iran to allow commercial shipping to resume through the strait, and to do so toll-free for the next 60 days.
In a social media post on Wednesday, President Donald Trump said Iran told him that there would be “no tolls, no insurance costs” and “no other charges of any kind” for ships traveling through the strait.
Claims to the contrary are “troublemaking” false reports, Trump said in the post.
In this June 27, 2016 file photo Alan Greenspan, former chairman of the Federal Reserve and president and founder of Greenspan Associates, speaks during a Bloomberg Television interview in Washington, D.C. (Andrew Harrer/Bloomberg via Getty Images, FILE)
(NEW YORK) — Alan Greenspan, the longtime chairman of the Federal Reserve, has died, his wife confirmed. He was 100 years old.
“Alan passed away at our home this morning at the age of 100 from complications of Parkinson’s Disease,” Andrea Mitchell, his wife and a chief correspondent at NBC News, said in a statement published by the network on Monday.
The economist is remembered for leading the American central bank amid periods of historic U.S. economic expansion, while critics have also said his policies contributed to and exacerbated the mortgage crisis and financial crash of 2008.
Greenspan, a libertarian Republican, became the 13th chairman of the Board of Governors of the Federal Reserve System two months before the stock market crash on Oct. 19,1987, known as Black Monday. He was credited with moving quickly to alleviate investors’ fears after the crash and was instrumental in ensuring the Federal Reserve made plenty of money available to alleviate the impact on financial markets. Stocks quickly rebounded.
He was appointed Fed chair by four different presidents during his career, first by Ronald Reagan in 1987. Greenspan continued to serve as Fed chairman under presidents George H. W. Bush, Bill Clinton and George W. Bush. He steered the U.S. economy through the economic boom in the 1990s, the dotcom bubble, and the Sept. 11, 2001, terrorist attacks. His final term as chair ended on Jan. 31, 2006.
Under his leadership, the Fed fostered a distaste for regulation and promoted very low interest rates in the early 2000s — two phenomena critics say encouraged a bubble in housing prices that eventually burst with disastrous effects on the global economy.
During his tenure, and before the financial crisis began, the nation experienced one of the longest periods of economic growth in its history.
A decorated economist, first inspired by music
Greenspan was born on March 6, 1926, in New York City, the only child of Herbert Greenspan, a stockbroker, and Rose Goldsmith Greenspan, a retail worker. His parents divorced when he was 4 years old, and he was raised mainly by his mother and his grandparents.
An aspiring musician, Greenspan attended Juilliard for a year and played saxophone and clarinet before dropping out and enrolling at New York University. He went on to gain his bachelor’s, master’s and doctoral degrees in economics from New York University. He also engaged in some advanced graduate work at Columbia University in New York, where he studied under the influential economist Arthur Burns.
Though short-lived, his music career was an influential portion of Greenspan’s life, and he considered the move into economics a logical progression. He saw the organization of economic data into sound fiscal modeling as analogous to the organization of musical notes into tunes, according to Greenspan biographer Justin Martin in his book, “Greenspan: The Man Behind Money.”
“I get the same kind of joy from solving a hard mathematical problem as I do from hearing a Haydn quartet,” Greenspan once told The New York Times Magazine.
Greenspan taught economics at NYU between 1953 and 1955 and then founded the economic consulting firm Townsend & Greenspan, where he served as chairman and president from 1954 to 1974. He returned to the firm in 1977 and stayed until 1987.
President Richard Nixon nominated Greenspan to chair the President’s Council of Economic Advisers in 1974, the first of many government economic positions he would hold. Nixon resigned as president hours after Greenspan was nominated, but he continued to serve under President Gerald Ford. Greenspan also served as a member of President Ronald Reagan’s Economic Policy Advisory Board and was a consultant to the Congressional Budget Office.
In the private sector, Greenspan served as corporate director for many companies, including Alcoa, General Foods and J.P. Morgan & Co. He also served as a member of Time magazine’s Board of Economists and a senior adviser to the Brookings Panel on Economic Activity.
In 2002, Greenspan received an honorary knighthood from Queen Elizabeth II in recognition of his contribution to global economic stability. In 2005, President George W. Bush presented Greenspan with the Presidential Medal of Freedom.
He held the position of Fed chairman from the time Reagan appointed him in 1987 until 2006, serving an unprecedented five terms under four presidents before being succeeded by Ben Bernanke.
Greenspan is credited by many with facilitating the longest economic expansion in U.S. history. One day after the Black Monday stock crash, Greenspan affirmed the Fed’s “readiness to serve as a source of liquidity to support the economic and financial system” and the central bank moved to encourage banks to lend on their normal terms. Unlike prior financial crises, the events of Black Monday notably were not followed by an economic recession or a banking crisis and less than two years later, the U.S. stock market surpassed its pre-crash highs.
During his tenure, Greenspan developed a reputation for being a consensus-builder and for his strong anti-inflation stance, focusing more on controlling prices than on promoting full employment. He led the Federal Reserve through several events with major economic consequences, including two U.S. recessions, the 1997 Asian financial crisis and the Sept. 11, 2001, terrorist attacks.
‘How could we have possibly got it so wrong?’
Starting in June 2003, the Federal Reserve set the federal funds rate, the rate at which banks typically borrow from each other, to one percent for a year. Though its intention was to lower the cost of borrowing and stimulate the economy, critics said the rate was too low and encouraged investments in risky subprime mortgage-backed securities, which they say contributed to the financial crisis in 2008.
The National Bureau of Economic Research, a research organization seen as an authority on measuring economic performance, later said that the recession officially began in December 2007.
In September 2007, Greenspan published a book that was both a memoir and economic commentary, “The Age of Turbulence: Adventures in a New World,” in which he criticized the George W. Bush administration for overspending and admitted that he supported the administration’s tax cuts without stressing the need for spending cuts.
In an interview with Bloomberg Businessweek in August 2012, Greenspan said, “one day before Lehman Brothers crashes, conventional wisdom was not even certain that we would fall into a recession.”
“In fact, we learned many months later that the downward trend had actually started,” Greenspan said. “How could we have possibly got it so wrong? I mean, I actually was saying, ‘Yes, recession is coming, not that we’re here yet.’ We didn’t know that it had already hit.”
In October 2008, Greenspan acknowledged to a congressional committee discussing financial regulation that, “I made a mistake in presuming that the self-interests of organizations, specifically banks and others, were such as that they were best capable of protecting their own shareholders and their equity in the firms.”
After Greenspan finished his term as chairman of the Federal Reserve in 2006, he established Greenspan Associates, an economic consulting firm in Washington, D.C.
With Greenspan as president, the firm had four employees as of October 2012. His client list has included giant finance clients like German firm Deutsche Bank and hedge fund Paulson & Co.
Personal life
Greenspan married artist Joan Mitchell in 1952. The couple divorced in 1953 after less than a year of marriage, and the marriage was later annulled. The two remained friends.
His first wife is remembered for introducing him to novelist and philosopher Ayn Rand, with whom Greenspan shared a friendship, a belief in free-market economic ideals and a philosophy of objectivism. In his 30s and early 40s, Greenspan spent many hours sitting with Rand’s band of followers, known as the “Collective,” discussing topics including politics philosophy, current events and economics.
In addition to Burns at Columbia, Rand and her group were instrumental in helping hone Greenspan’s capitalist, free-market economic philosophy, according to Martin, Greenspan’s biographer.
The group’s open style of debate and discussion served Greenspan well in his various governmental roles. During his career in public service, he became known for a well-developed ability to communicate with Congress without offending those with opposing viewpoints or politicizing his messages.
Though he was said to back revamping the Social Security system and raising the retirement age, Greenspan was wary of how his public statements as Fed chairman might move markets. He rarely granted interviews. He was known for making openly ambiguous public statements about the state of the U.S. economy, once telling Congress, “If I’ve made myself too clear, you must have misunderstood me.”
Greenspan married NBC News correspondent Mitchell in 1997. Their marriage was officiated by the late Supreme Court Justice Ruth Bader Ginsburg.
“We’ve had the most wonderful marriage,” he told Bloomberg Businessweek in August 2012. “It gets better every year. We’re still very much together in love.”
Kevin Warsh, Chair of the Federal Reserve, on April 21, 2026 in Washington, DC. (Photo by Andrew Harnik/Getty Images)v
(WASHINGTON) — The Federal Reserve is set to announce its latest decision on interest rates on Wednesday as the central bank weathers the highest inflation in three years.
The announcement will mark the first possible adjustment of the benchmark interest rate since Trump nominee Kevin Warsh began his four-year term as Fed chair last month.
The policy move is also set to arrive at a moment of flux for the nation’s economy, just days after an agreement between the United States and Iran offered hope for some price relief.
The U.S.-Iran accord, set to be formally signed on Friday, came as gasoline prices fell below $4 a gallon for the first time since March. Still, fuel costs stand well above pre-war levels, and an array of grocery prices remain elevated.
Futures markets overwhelmingly expect the Fed to hold interest rates steady when policymakers meet on Wednesday, according to the CME FedWatch Tool, a measure of investor sentiment.
In recent weeks, however, odds have risen for a potential interest rate hike by the end of 2026, the tool showed, granting a roughly four in 10 chance of a quarter-point increase in December.
The shift in expectations came after a stronger-than-expected jobs report earlier this month showed robust hiring in May. In theory, a resilient labor market could afford central bankers leeway to raise interest rates in an effort to dial back inflation, since elevated borrowing costs risk a hiring slowdown.
Inflation jumped for a third consecutive month as the Iran war continued to drive up prices in May, surpassing 4% for the first time in three years
The Middle East conflict prompted the Iranian closure of the Strait of Hormuz, a maritime trading route that facilitates the transport of about one-fifth of global oil supply. The standoff triggered one of the largest oil shocks ever recorded, sending gasoline prices surging.
On Monday, President Donald Trump announced a U.S.-Iran deal that included plans to reopen the strait. Iranian Deputy Foreign Minister Kazem Gharibabadi confirmed the deal had been finalized and said it would be signed in Switzerland on Friday. Oil prices fell to their lowest level since March.
The benchmark rate stands at a level between 3.5% and 3.75%. That figure marks a significant drop from a recent peak attained in 2023, but borrowing costs remain well above a 0% rate established at the outset of the COVID-19 pandemic.
The rate decision will be the first major policy move overseen by Warsh, who will address reporters during a customary press conference minutes after the central bank issues its announcement.
During his term as a Fed governor in the late 2000s and early 2010s, Warsh gained a reputation as an interest-rate “hawk,” meaning he generally preferred higher interest rates as a means of ensuring low and stable inflation.
Last year, Warsh voiced support for lower interest rates. At his Senate confirmation hearing in April, Warsh emphasized the threat posed by elevated inflation.
“When inflation surges — as it has done in recent years — grievous harm is done to our citizens, especially to the least well-off,” Warsh said.
Bucking typical norms, former Fed Chair Jerome Powell Powell will cast a vote on interest rates as a member of the Fed’s 12-person policymaking board.
Powell said he would stay on at the central bank’s board of governors after his term as chair expired as an investigation into the Fed’s office renovation continues.
The Department of Justice moved to drop a criminal probe into Powell in April, calling on the Fed’s inspector general to carry out the investigation into cost overruns tied to the renovation. Powell will remain on the Fed’s board for an indeterminate length of time, he said last month.
The criminal investigation into Powell focused on alleged false testimony to Congress about an office renovation. Powell, who was appointed by Trump in 2017, has rebuked the probe as a politically motivated effort to influence interest-rate policy. Trump denied any involvement in the criminal investigation.
A pumpjack stands idle in the Huntington Beach oil field on April 23, 2026 in Huntington Beach, California. (Mario Tama/Getty Images)
(NEW YORK) — Oil prices on Monday fell to their lowest level since March after U.S. officials announced an agreement between the United States and Iran.
West Texas Intermediate futures price, the benchmark index for U.S. trading, registered at about $80.40. That figure, which amounted to a 5% drop on Monday, marked the lowest price since March 5, just a week after the outbreak of the Iran war.
Stock prices, meanwhile, climbed on hopes of a resolution to the Iran war. The Dow Jones Industrial Average jumped 530 points, or 1%, while the S&P 500 increased 1.4%. The tech-heavy Nasdaq rose 2.3%.
Gas prices have fallen toward $4 per gallon in recent weeks, nearing the milestone as oil costs have eased in response to negotiations between the U.S. and Iran.
The national average price of a gallon of gas stands at $4.06, marking a decline of 46 cents, or 10.2%, over the past month, AAA data showed. Gas prices, however, remain $1.08 higher than where they stood before the Iran war.
The Middle East conflict prompted the Iranian closure of the Strait of Hormuz, a maritime trading route that facilitates the transport of about one-fifth of global oil supply. The standoff triggered one of the largest oil shocks ever recorded, sending gasoline prices higher.
President Donald Trump said in a Sunday social media post that the U.S. and Iran had reached a deal that will open up the strait.
“I hereby fully authorize the toll free opening of the Strait of Hormuz, and, simultaneously herewith, authorize the immediate removal of the United States Naval blockade,” Trump wrote.
“Ships of the World, start your engines. Let the oil flow!” he added.
Iranian Deputy Foreign Minister Kazem Gharibabadi confirmed the deal had been finalized and said it would be signed in Switzerland on Friday.
Trump said the strait would open after the formal signing of the deal on Friday. The oil flow is linked to mine removal, Trump noted.
Crude oil is the main ingredient in auto fuel, accounting for more than half of the price paid at the pump, according to the federal U.S. Energy Information Administration.
The U.S. is a net exporter of petroleum, meaning the country produces more oil than it consumes. But since oil prices are set on a global market, U.S. prices move in response to swings in worldwide supply and demand.
ABC News’ David Brennan and Isabella Murray contributed to this report.
Fuel prices are displayed at a gas station on June 09, 2026 in Chicago, Illinois. (Scott Olson/Getty Images)
(NEW YORK) — Consumer sentiment improved in June for the first time since the outbreak of the Iran war as gasoline prices eased in recent weeks, but shopper attitudes remained near their worst level on record, University of Michigan survey data on Friday showed. The reading exceeded economists’ expectations.
The survey snapped three consecutive months of dampening consumer sentiment, recovering from an all-time low in May, data showed. The University of Michigan has conducted the survey for the past 80 years.
This improvement in sentiment was widespread, seen across age, education and political party, Surveys of Consumers Director Joanne Hsu said in a statement. Overall assessments and expectations of personal finances and business conditions all rose in June, she noted.
The fresh figure comes days after a government report on inflation showed the pace of price increases exceeded 4% for the first time in three years.
Prices rose 4.2% in May compared to a year earlier, increasing 0.5% from the prior month, according to U.S. Bureau of Labor Statistics data.
Consumers expect inflation to move higher over the next year, hitting a pace of 4.8% in June 2027, the University of Michigan survey showed.
The Middle East conflict prompted the Iranian closure of the Strait of Hormuz, a maritime trading route that facilitates the transport of about one-fifth of global oil supply. The standoff triggered one of the largest oil shocks ever recorded, sending gasoline prices higher.
Drivers stung by high gas prices have enjoyed some welcome relief over recent weeks, however, even as the impact of the Iran war continues to choke off oil supply.
The national average price of a gallon of gas stands at $4.10, marking a decline of 40 cents, or 8.8%, over the past month, AAA data showed. Gas prices, however, remain $1.12 higher than where they stood before the Iran war.
Consumer spending, which accounts for about two-thirds of U.S. economic activity, could weaken if shopper remains lackluster.
Spending slowed over the first three months of 2026 compared to the previous three-month period, according to government data issued earlier this year. The economy remained solid at the outset of this year, however, as gross domestic product rose 2% on an annualized basis, the report showed.